Retirement planning for women starts with an uncomfortable piece of math: we live longer and we retire with less. The first half is biology. Women outlive men by about five years on average, and more than 70 percent of women wish they had started investing earlier ., BNN Bloomberg reports. The second half is a gap we can close. Because the math is on a calendar, not a mystery, the fix starts with planning.
I opened my first retirement account at 38 and spent a year regretting the late start. Then I calculated what automation could do with the time I had left. The regret faded quickly. The habits I set up that year now do more work than any single decision I made in my twenties.
The Longevity Math Behind Retirement Planning for Women
Here is the math nobody prints on a statement. A man and a woman with identical savings will fund different retirements, because her lifetime is roughly five years longer. Those five extra years multiply every cost: housing, healthcare, and daily living all extend. When the same money must cover a longer period, every percentage point of return matters twice.
The health dimension makes it harder. Women spend 25 percent more of their lives in poor health, so the later years of a retirement need more care spending, not less ., according to McKinsey. This is why planning for retirement and planning for health are the same discipline. You cannot fund a long life without protecting the body that lives it.
Why Women Save More but Plan Less
Women have a strange advantage and disadvantage at the same time. We tend to save more of our income than men do, according to repeated household studies. However, we often leave those savings in cash, emergency accounts, and short-term instruments. Because cash pays little and inflation taxes the rest, saving without planning quietly loses ground.
I saw this pattern in my own family. My aunt saved faithfully for thirty years and retired with a comfortable sum in cash. The purchasing power of that sum shrank every year, and her options narrowed with it. When I asked why she never invested, she said nobody ever showed her how. That sentence is the whole problem in eleven words.
The 3 Levers: Time, Automation, Consistency
Three levers control the outcome, and only one of them is luck. Time is the first lever: the years you have left, which grow shorter every birthday. Automation is the second: the system that invests before you can hesitate. Consistency is the third: the habit that outlasts every market mood. Because two of the three are fully in your control, the plan writes itself.
The employer match deserves its own paragraph. If your workplace offers one, contribute at least enough to capture it fully, because matching money is a guaranteed return. I increased my contribution by one percent every January, a step so small I never felt it. Over the years, that tiny ladder moved me years ahead of schedule.
Micro-Investing: Small Amounts, Real Compound
The size of the contribution matters less than the regularity. Here is an illustrative example, not a promise: 500 dollars a month invested at 8 percent for 25 years grows to roughly 470,000 dollars. Skip that same amount and the difference is the entire sum. Because the numbers scale down gracefully, a smaller monthly amount still produces a serious future. Which is why starting late still works, as long as the start actually happens.
I practice this with micro-investing myself. Round-ups from everyday purchases, small weekly transfers, and bonus days all feed the same account. The amounts feel like nothing individually. However, they arrive on schedule, and schedule is the real investor. Over a decade, the micro amounts become macro.
The Order of Operations
Before any retirement money moves, the emergency fund must exist. A retirement plan without a safety net is a plan that collapses at the worst moment. Our guide to the emergency fund explains the size and the psychology . Once the buffer is in place, the retirement contributions can run without interruption.
After the buffer, the order is simple. Capture the match, automate the base contribution, and raise the rate with every raise. Then add the generational layer: our guide on building generational wealth shows how retirement money becomes family money . Because the structure compounds, the order matters more than the amounts.
A One-Page Plan for Your 40s
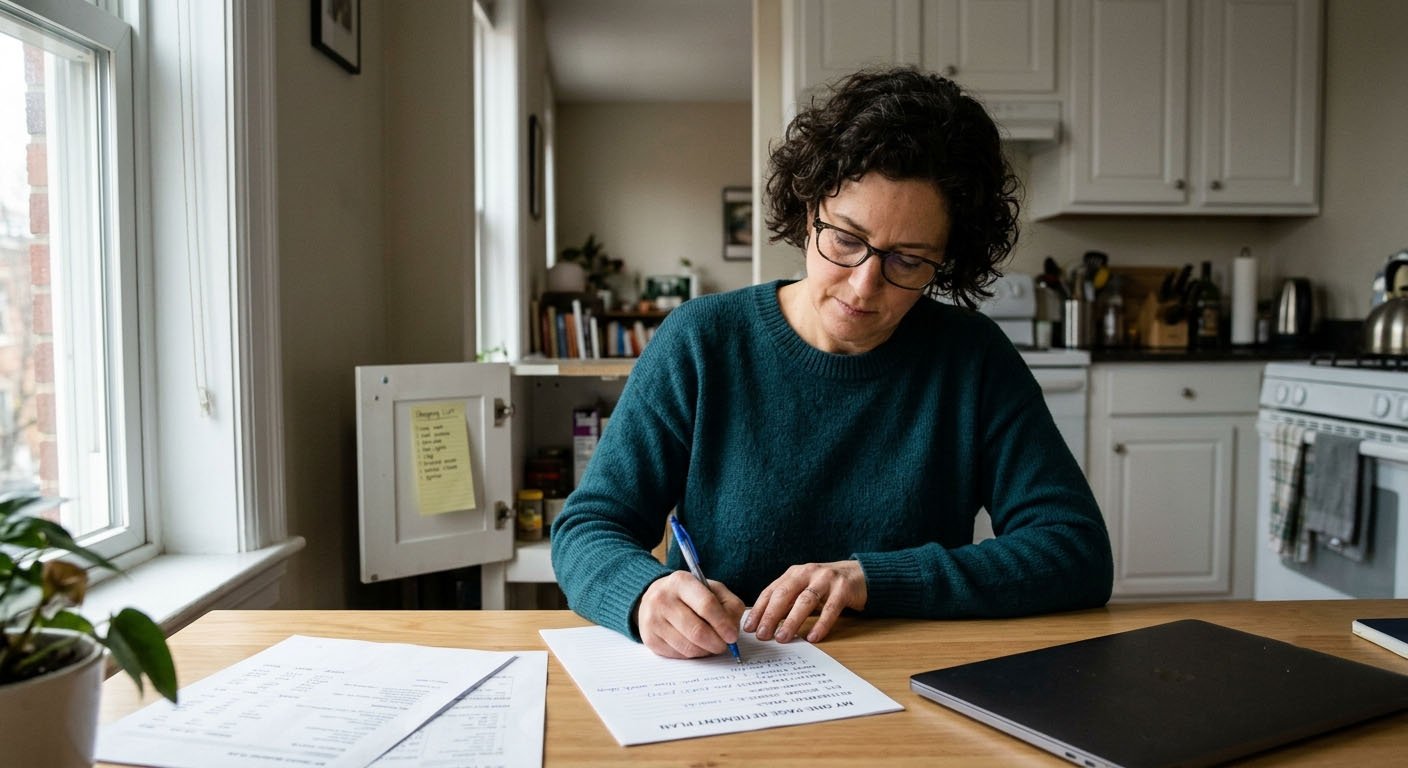
You can build the whole plan on one page. First section: income minus fixed costs, with the surplus automated into retirement. Second section: the emergency fund balance, checked every quarter. Third section: the one-page list of accounts, beneficiaries, and passwords. Because the plan fits on a page, it survives real life.
I keep mine taped inside a kitchen cabinet, where I see it every morning. That single habit did more for my retirement than any seminar ever did. The paper is ordinary, but the visibility is the magic. If you take one action this month, make it this: write your own page and tape it somewhere you look daily. Then the math will do the heavy lifting for the next twenty-five years.
Retirement planning for women is not a punishment for living longer. It is the upgrade that makes those extra years worth funding. Because the time is still on your side at 35, 40, or even 50, start with the automation, protect the buffer, and let the calendar work. Your future self is watching the clock with you.
Written by Maya Torres for March-8.
This iss verry attention-grabbing, You’re ann excessively professional blogger.
I have joined your rss feed annd look forward to in search of extra off your great post.
Also, I hve shared your web sie in my social networks auroravpn